The key insights for waterfront buyers in the Middle Keys come down to three checks: whether the water access actually fits your vessel, what the current flood-zone and elevation records say, and whether insurers will cover the home at replacement value. Verify all three before your inspection and financing contingencies expire.
What are the key insights for waterfront buyers in the Middle Keys luxury market?
Key insights for waterfront buyers in the Middle Keys come down to three checks: whether the water access actually fits your vessel, what the current flood-zone and elevation records say, and whether insurers will cover the home at replacement value. Everything else, from finishes to the pool deck, is secondary to those three. Verify them before your inspection and financing contingencies expire.
Key Takeaways
Recent local market data for Marathon shows a median sale price of $955,000 and a median of 45 days on market across 84 homes sold in roughly the last 90 days.
That median is an area-wide figure, not a luxury benchmark, so a waterfront estate has to be priced against comparable water frontage, access, and construction, not against the average.
Monroe County published new preliminary coastal flood maps in September 2026, so any older flood-zone information in a listing needs to be re-verified.
"Waterfront" in a listing does not prove usable boating access, so dock rights, canal depth, bridge clearance, and the route to open water all need independent confirmation.
Insurance feedback should come before your contingencies expire, because flood and windstorm terms on a high-value home can change the carrying cost of the whole purchase.
How should you read the Middle Keys luxury market before making an offer?
Read it property by property, not by average. Recent local market data for Marathon shows a median sale price of $955,000, a median of 45 days on market, 31 new listings in the last 30 days, and 84 homes sold over roughly the last 90 days. Those figures describe the area. They do not describe a canal-front home with a deeded dock or a Gulf-front lot with a seawall.
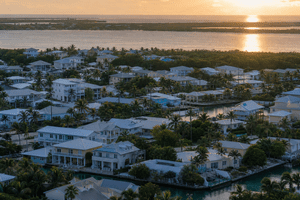
Marathon sits roughly between Mile Marker 47 and Mile Marker 60, and it is often evaluated as a more space-oriented, boating-focused alternative to the denser, higher-profile markets farther north and south in the Keys. That comparison only holds up when you run it against the specific house: water access, lot configuration, privacy, construction quality, insurance, and carrying costs. Asking price alone tells you very little.
Luxury waterfront is its own asset class, and we advise on it with property-level data rather than area averages. Here is how the nearby markets in our service area compare at a glance, using aggregated public listing data for the trailing 90 days as of October 2026:
Area Median Sale | Price Median | Days on Market
Key Colony Beach $1,113,500| 63
Duck Key | $617,000| 46 (townhomes)
Islamorada $1,030,000 | 49
Treat these as area-level medians. They blend every property type that closed, and an individual home's value depends on condition, street, build year, and timing. One high-end waterfront sale can sit far from any of these numbers, which is why a local comparative analysis matters more than a headline median. If you want to see what's on the market now, start with our featured Duck Key property listings, then we can build a comparison around the homes that fit your boat and your plans.
How do you verify water access, dockage, and flood exposure on a waterfront home?
Verify each one independently, with documents and a boat-level look at the water, not with the listing description. We walk our clients through this before they ever write an offer, because this is where luxury purchases go wrong.
Is the dock actually yours, and does the water work for your vessel?
Start by confirming whether the dock is private, shared, deeded, licensed, or subject to separate association or marina rules. Then have the dock, pilings, seawall, boat lift, and electrical service inspected on their own. A hull-and-engine buyer cares about different things than a paddleboard buyer, so define your intended use first.
Ask for the navigational details in writing or confirm them on the water:
The route from the dock to open water
Fixed-bridge clearance for your vessel
Canal depth and tidal limitations
Whether the lift and dock can handle the boat you own or plan to buy
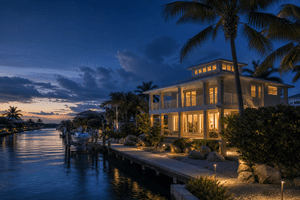
An attractive waterfront position can offer very different boating utility than the house next door. Open-water, bayfront, Gulf-front, canal-front, and marina-connected properties each differ in views, exposure, dock protection, and day-to-day usability. Local market coverage notes that luxury listings commonly emphasize open-water or canal-front positioning, private dockage, boat lifts, and the difference between protected and exposed dockage. Those are feature observations, not verified price premiums. We do not assign a dollar value to a dock or lift without property-specific evidence.
What flood zone is the home in, and what changed in 2026?
Get the current FEMA and county flood-zone information, elevation documentation, any prior flood claims available, and the applicable survey or certificate. Monroe County released information on new preliminary coastal flood maps in September 2026. Preliminary maps can change before adoption, so don't rely on an older listing for the zone or elevation. Verify the applicable map during due diligence.
The county advises owners to know their flood risk and to discuss coverage with an insurance professional. It also states that a property in a Special Flood Hazard Area is five times more likely to experience a flood than a fire. Monroe County keeps additional public resources on flooding and FEMA mapping that are a sound starting point for evaluating a parcel.
What should you know about insuring a high-value waterfront home?
Request an insurance review early, before your inspection and financing contingencies expire. Monroe County participates in the National Flood Insurance Program, so federally backed flood insurance is available to eligible property owners. Availability and terms for your specific high-value property still have to be confirmed with insurers.
Ask about flood, windstorm, property, liability, and replacement-cost coverage together. A home that looks perfect can become a very different purchase once the coverage picture is clear. This is the one conversation we never let a buyer postpone.
What does the purchase sequence look like for a luxury waterfront home?
Work in this order, and don't make the offer non-contingent until the last step is done. Here are the key insights for waterfront buyers, in sequence:
Define your boating use. Vessel size, draft, and how often you'll run it.
Identify the waterfront submarkets that fit that use: Gulf-front, bayfront, oceanfront, canal-front, or marina-connected.
Get insurance and flood-zone feedback before you commit to a number.
Review elevation, survey, dock, seawall, and permit records. Your closing agent and title review will surface part of this, but the physical records need your own attention.
Inspect structure, electrical, roof, seawall, dock, and marine systems.
Validate financing, rental assumptions, and resale considerations against what the inspections and insurers told you.
What should you inspect for storm resilience?
Look at roof age and attachment, impact-rated windows and doors, shutters, generator systems, drainage, seawalls, docks, corrosion, and mechanical equipment exposed to salt air. These items affect maintenance, insurability, and storm recovery. Rebuild potential after a major storm deserves its own conversation, because what you may be allowed to rebuild depends on the property's records and current rules. Confirm it for your specific parcel before you rely on it.
Can a luxury waterfront home double as a vacation rental?
Sometimes, but treat rental income as an assumption to test, not a given. Confirm the rules that apply to the specific property with the city, the county, and any association before you build a return on it. Then stress-test the carrying costs, including insurance, against a conservative rental scenario. We'll run those numbers with you before you make an offer.
Prefer to hear from people who've worked with us? You can read our reviews on Google.
FAQ
What should I check before buying a luxury waterfront home in Marathon?
Check the water access, flood zone and elevation records, and insurance availability before anything else. Then inspect the dock, seawall, lift, roof, and impact openings separately from the main house. Because Monroe County released preliminary coastal flood maps in September 2026, confirm which map applies to your property today.
How do I compare open-water, bayfront, and canal-front properties in the Middle Keys?
Compare them on exposure, dock protection, route to open water, and views, not on the word "waterfront." Open-water and bayfront positions can offer broader views but more exposure, while canal-front lots can offer more protected dockage with a longer run to open water. The right choice depends on your vessel and how you plan to use it.
What does a private dock or boat lift add to a waterfront home's value?
There is no verified Middle Keys dollar premium we can hand you for a dock or lift in general. Its value depends on the dock's condition, the water depth, the lift capacity, and whether your boat can use it. We evaluate it against comparable sales of similar frontage and access, which we can walk through with you for a specific home.
How can I verify whether a Middle Keys property has usable deep-water access?
Confirm the route to open water, canal depth, tidal limitations, and fixed-bridge clearance, and have someone run the route with a vessel like yours if you can. Listing language is not proof of boating utility. Monroe County's flooding and mapping resources help with exposure, but depth and clearance need an on-the-water check.
How do I insure a high-value waterfront home in Monroe County?
Start the insurance conversation before your contingencies expire. Monroe County confirms that NFIP flood coverage is available to eligible owners, but terms for a particular high-value property have to be confirmed with insurers. Ask about flood, windstorm, liability, and replacement-cost coverage together, and confirm the current flood map first, given the September 2026 preliminary maps.
The key insights for waterfront buyers aren't complicated, but they are easy to skip when a view is doing the talking. Verify the water, the flood map, and the insurance first, and the rest of the decision gets much clearer. Our team has closed over $700 million in sales across the Keys, and we'd like to run this checklist with you against the actual homes you're considering. Schedule a consultation with The Brenner Scheel and Casey Team at 305-783-3395.
About The Brenner Scheel and Casey Team
Kristen Brenner, with Tierce Scheel and Margie Casey, leads The Brenner Scheel and Casey Team, the #1 selling team on Duck Key, with over $700 million in closed sales. As Certified Luxury Home Marketing Specialists, they focus on waterfront estates, luxury residences, and high-performing vacation properties from Key Largo to Key West. Duck Key Realty, founded by the Brenner family in 1977, has operated continuously for nearly five decades from its home office on the Overseas Highway in the Middle Keys.
Duck Key Realty | Florida Keys Real Estate Group · 305-783-3395
Equal Housing Opportunity. Kristen Brenner, Broker / Owner, Duck Key Realty | Florida Keys Real Estate Group. This article is general information, not legal, tax, or financial advice. Confirm your own numbers with your closing agent, tax advisor, insurance professional, or lender.